
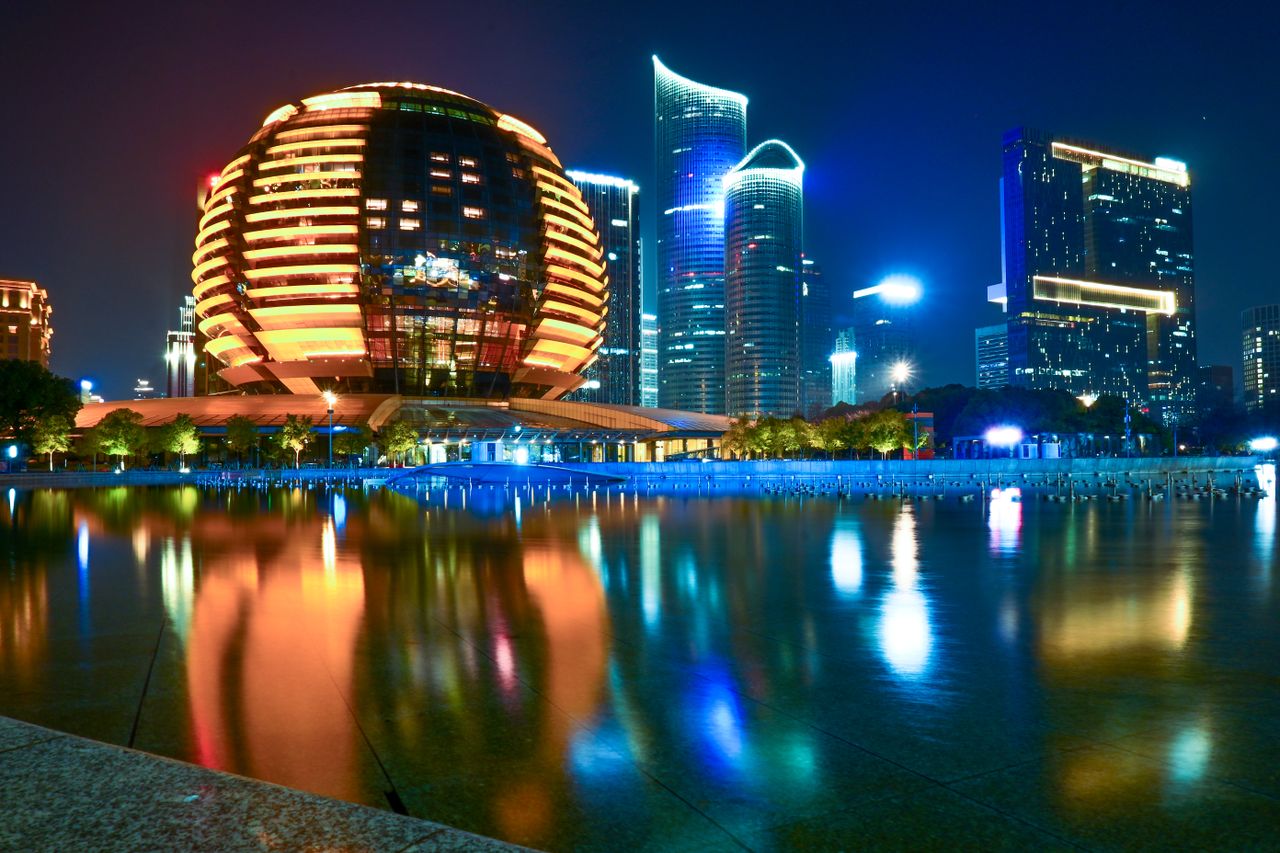
When global executives think about China’s technology and e-commerce ecosystem, most instinctively picture Shenzhen or Beijing. Hangzhou rarely gets the spotlight it deserves. That is a costly oversight. This city of 12 million people in Zhejiang Province is home to Alibaba Group, Ant Group, NetEase, Hikvision, and a dense cluster of digital commerce infrastructure companies that collectively process more gross merchandise value each year than the entire US e-commerce market. Understanding Hangzhou is not optional for any serious student of global digital trade — it is foundational.
From Silk to Software: Hangzhou’s Commercial DNA
Hangzhou has been a commercial powerhouse for over a thousand years. During the Song Dynasty (960-1279 AD), the city served as China’s imperial capital and was celebrated by Marco Polo as one of the most magnificent cities in the world. Its prosperity was built on silk, tea, and the sophisticated merchant culture that defined the Yangtze River Delta’s economic identity for centuries. That same entrepreneurial instinct explains why Zhejiang Province consistently produces more private enterprises per capita than any other province in China — and why Hangzhou became the natural home for China’s defining digital commerce platform.
Today Hangzhou contributes approximately RMB 2.1 trillion (roughly $290 billion) to China’s GDP annually, making it one of the wealthiest prefectural-level cities in the country. The digital economy accounts for more than 27 percent of that total — a proportion that exceeds most major Western financial centers. The city hosts over 700,000 registered companies, a figure that has more than doubled since Alibaba’s 2014 New York Stock Exchange IPO placed Hangzhou firmly on the global investment map.
Alibaba: The Company That Defined an Era
Jack Ma founded Alibaba in a Hangzhou apartment in 1999 with 18 co-founders — an unlikely mix of English teachers, engineers, and salespeople united by the conviction that the internet could democratize trade for small and medium-sized enterprises. Within five years the company had launched Taobao (C2C commerce), Alipay (digital payments), and Tmall (B2C brand commerce) — a trifecta of platforms that would eventually process more transactions annually than eBay and Amazon combined.
At its peak market capitalization in 2020, Alibaba was valued at approximately $860 billion. The subsequent regulatory crackdown — including the blocked Ant Group IPO and a record RMB 18.2 billion antitrust fine — recalibrated the company’s strategic posture. By 2026, Alibaba has restructured into six independent business units under CEO Eddie Wu, refocusing on cloud computing, international commerce, and logistics infrastructure. The company generates approximately $130 billion in annual revenue and operates across 200 countries.
Tmall Global remains the preferred entry channel for international brands seeking Chinese consumers — over 29,000 overseas brands sell through the platform. Alibaba International Digital Commerce Group, operating AliExpress, Lazada (Southeast Asia), and Trendyol (Turkey), represents China’s most ambitious cross-border retail infrastructure. Any Western company sourcing from China or selling into Asia-Pacific markets is already operating within Alibaba’s gravitational field, whether they recognize it or not. Our detailed analysis of Alibaba’s e-commerce vision and strategic evolution covers the full arc of the company’s growth and what it means for global commerce practitioners.
Ant Group and the Financial Infrastructure Layer
Alibaba’s financial affiliate Ant Group — operator of Alipay — is headquartered in Hangzhou and represents one of the most significant financial technology infrastructure stories of the past two decades. Alipay launched in 2004 as an escrow service to solve the trust problem inherent in online transactions between strangers. By 2026, it processes over RMB 100 trillion in annual payment volume and has expanded into wealth management (Yu’ebao money market fund), insurance, consumer credit (Huabei), and small business lending (MYbank).
The abandoned 2020 IPO — which would have been the world’s largest at an estimated $37 billion raise — marked a turning point. Regulators required Ant Group to restructure as a financial holding company subject to capital requirements comparable to traditional banks. That restructuring, now largely complete, has produced a more compliant entity with a more cautious international expansion posture. For global fintech operators and foreign banks seeking partnerships in China’s digital payment ecosystem, understanding Ant Group’s current regulatory constraints is as important as understanding its technical capabilities and scale advantages.
Beyond Alibaba: Hangzhou’s Broader Tech Ecosystem
Hangzhou would be a significant technology city even without Alibaba. NetEase, China’s second-largest gaming and internet company (revenue: approximately $14.3 billion in 2024), relocated its headquarters from Guangzhou to Hangzhou in 2019, attracted by talent density and proximity to Alibaba’s engineering ecosystem. NetEase Cloud Music claims over 200 million monthly active users and competes directly with Tencent Music for China’s digital audio market.
Hikvision and Dahua Technology — the world’s two largest manufacturers of video surveillance equipment — are both headquartered in Hangzhou. Hikvision alone generates annual revenue exceeding $12 billion and holds more than 25 percent of the global CCTV camera market. Both companies face US Entity List designations related to security concerns, creating a compliance environment that Western integrators and procurement teams must assess carefully before any sourcing or deployment engagement.
DingTalk, Alibaba’s enterprise collaboration platform, competes with Microsoft Teams and Slack across Chinese enterprises and has expanded into Southeast Asian markets. With over 700 million registered users in China, DingTalk’s integration with Alibaba Cloud’s enterprise workflow tools makes it a de facto operating system for small business administration across much of Chinese-speaking Asia.
Hangzhou’s Cross-Border E-Commerce Infrastructure
China’s State Council designated Hangzhou as one of the first Cross-Border E-Commerce Comprehensive Pilot Zones in 2015. The designation has since expanded into a mature infrastructure cluster that processes an estimated $25 billion in annual cross-border transaction value. The Hangzhou pilot zone model — integrating customs clearance, bonded warehousing, foreign exchange settlement, and digital tax refund systems into a unified administrative framework — has been replicated across 165 designated zones nationwide.
For foreign exporters selling into China via cross-border e-commerce channels, the Hangzhou infrastructure represents a lower-barrier entry path than traditional general trade. Small-format shipments to Chinese consumers can be declared, taxed, and cleared in hours rather than days. China’s Ministry of Commerce publishes detailed pilot zone operational guidelines at mofcom.gov.cn — essential reading for any foreign brand evaluating a China digital commerce entry strategy. We covered the national policy context in our analysis of China’s 165 cross-border e-commerce pilot zones and their impact on global trade infrastructure.
Zhejiang Province: The Entrepreneurial Context
Hangzhou’s success is inseparable from its provincial context. Zhejiang is China’s most entrepreneurial province by almost any metric: private enterprises generate over 70 percent of provincial GDP, compared to a national average closer to 60 percent. The province is home to Yiwu — the world’s largest small commodities wholesale market — Ningbo (one of the world’s busiest container ports), and Wenzhou, historically synonymous with China’s private banking culture.
This entrepreneurial density creates a talent and supply chain ecosystem that reinforces Hangzhou’s digital economy. Software engineers trained at Zhejiang University (consistently ranked among China’s top five institutions for engineering) find immediate placement within a city whose largest employer is one of the world’s most technically sophisticated companies. Our deeper dive into Guangdong vs. Zhejiang as China’s two export powerhouses provides essential context for sourcing executives navigating regional commercial culture differences.
What Foreign Businesses Must Know When Engaging Hangzhou
Hangzhou’s business culture reflects Zhejiang Province’s commercial pragmatism. Meetings move faster than in Beijing and Shanghai. Decision-making authority is often concentrated in a founder or senior executive rather than distributed through committee structures common in state-owned enterprise environments. Speed, execution, and measurable outcomes are valued more explicitly than in Northern Chinese business culture, where relationship cultivation traditionally precedes commercial discussion.
Three practical realities govern engagement with Hangzhou-based firms in 2026. First, Alibaba and its ecosystem companies expect Western counterparts to engage with platform data and analytics tools seriously — arriving at a partnership discussion without having analyzed your Tmall or AliExpress performance signals unpreparedness that will be noticed. Second, Ant Group’s compliance transformation has made financial partnerships substantially more documentation-intensive than they were pre-2021. Third, Hikvision and Dahua present compliance risks for US-headquartered companies that must be assessed under Bureau of Industry and Security export control regulations before any procurement or integration engagement.
The US-China Business Council maintains active resources on navigating these compliance dynamics at uschina.org — a reference point no executive building an engagement strategy with Hangzhou’s tech sector should overlook. For broader regional manufacturing context, our analysis of China’s regional industrial clusters provides useful comparative framing for the Yangtze River Delta ecosystem that Hangzhou anchors.