
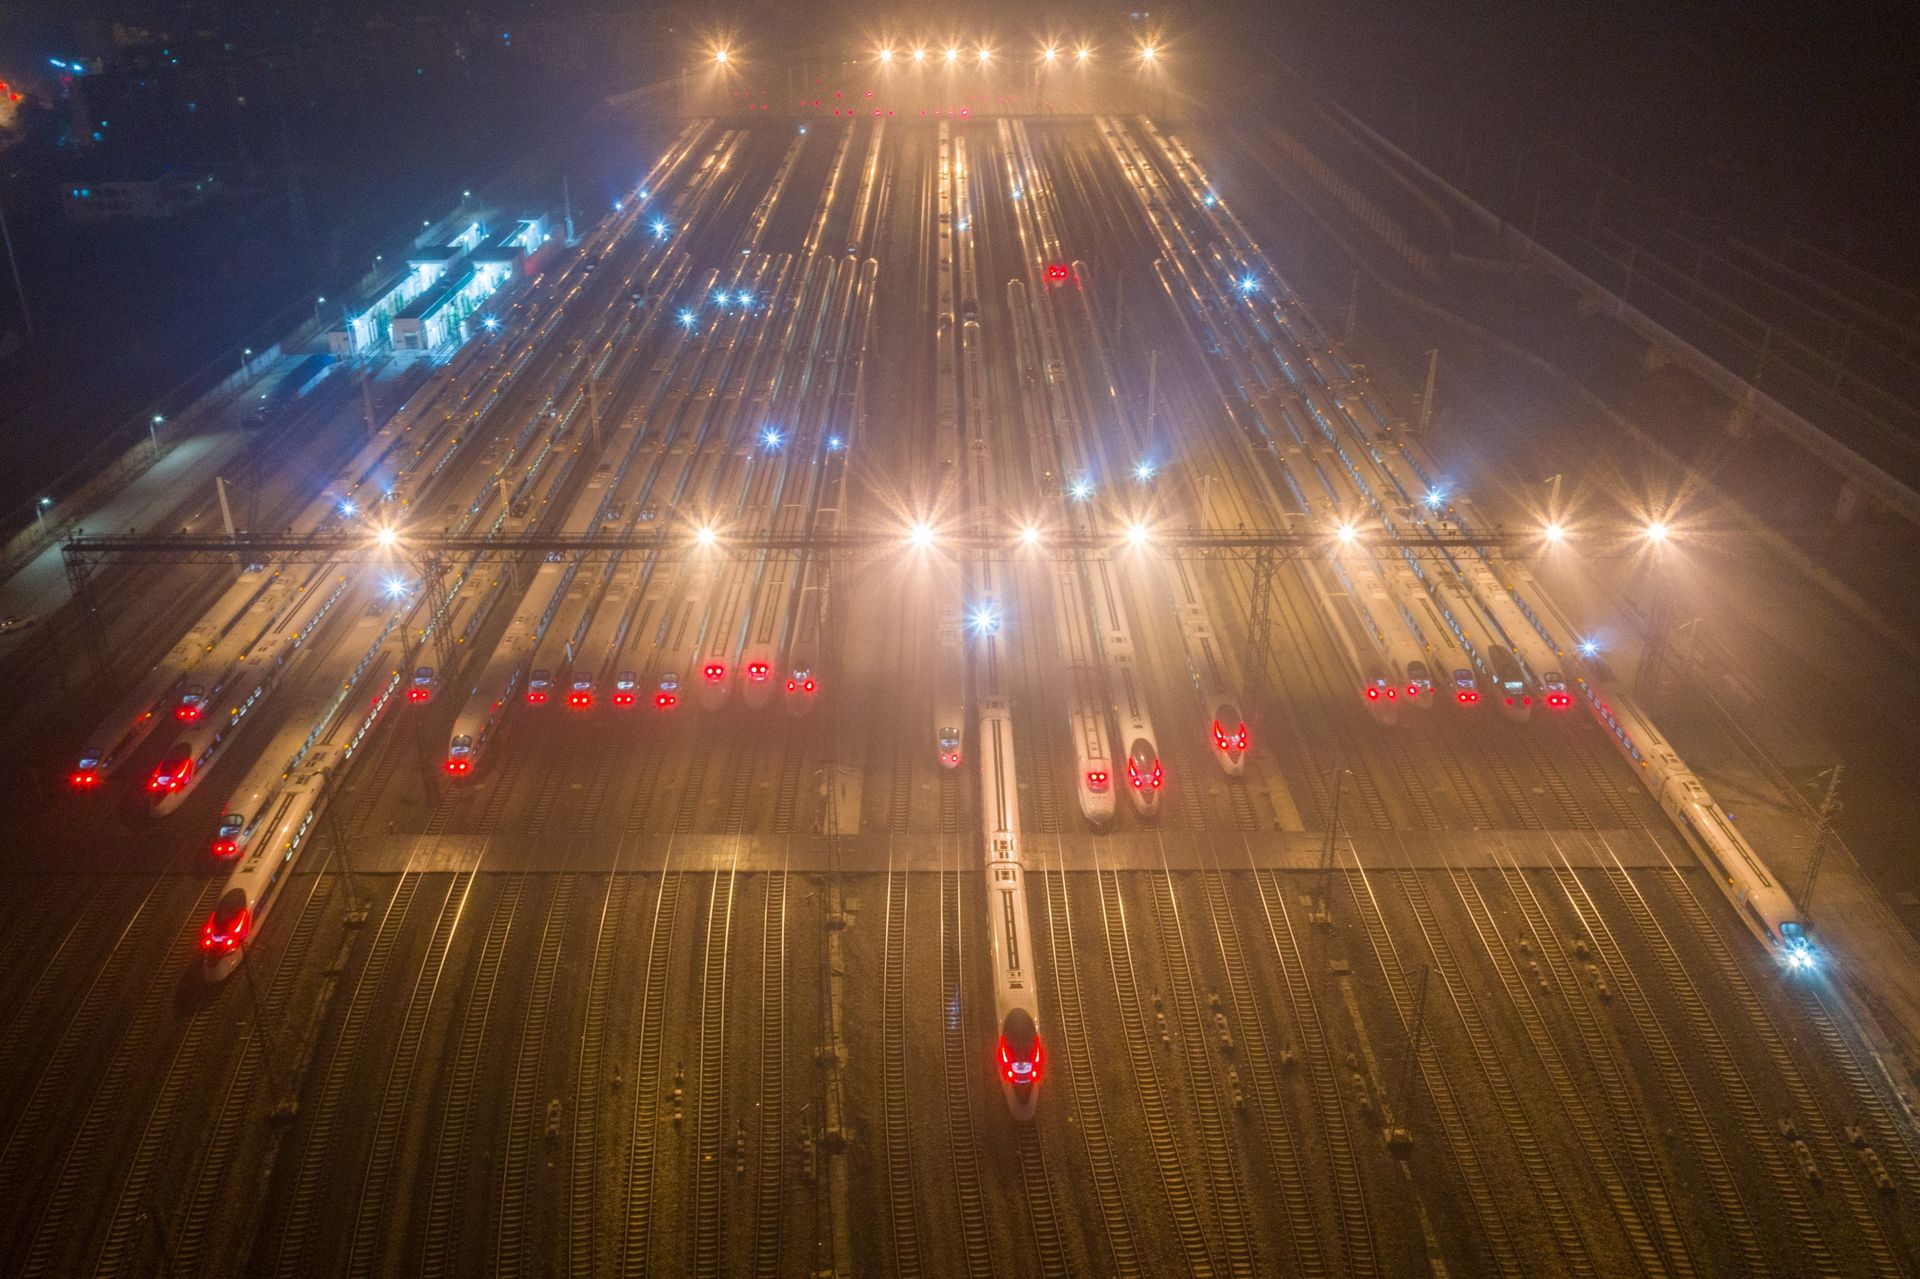
When China launched its first dedicated high-speed rail line between Beijing and Tianjin in August 2008 — just days before the Olympic opening ceremony — the 350 km/h service was as much a political statement as a transport solution. Eighteen years later, that single 120-kilometer corridor has multiplied into a 46,000-kilometer network that carries more passengers annually than the entire global aviation industry combined. For foreign executives, infrastructure investors, and trade strategists, the maturation of China’s HSR network is no longer a curiosity. It is a competitive variable that directly affects labor costs, supply chain geography, real estate valuations, and investment return profiles across the world’s second-largest economy.
The Scale That Changes Everything
As of mid-2026, China operates approximately 46,000 kilometers of high-speed rail — lines capable of operating at 250 km/h or above. This represents roughly two-thirds of all high-speed rail in operation worldwide. The next-largest network, in Europe, totals approximately 11,000 kilometers across more than a dozen countries. Japan, where the concept was pioneered with the Shinkansen in 1964, operates roughly 3,000 kilometers.
Annual ridership on China’s HSR network reached 3.8 billion passenger-trips in 2023, according to the National Railway Administration of China, recovering strongly through 2025 as domestic travel normalized. The International Air Transport Association reported global air passenger numbers of roughly 4.5 billion in 2023 — meaning China’s high-speed trains alone accounted for nearly 85 percent of total global aviation throughput in passenger-trips.
The financial architecture behind this network is substantial. China State Railway Group carries approximately RMB 6 trillion (roughly $830 billion) in total liabilities, much of it accumulated through bond issuances and policy bank loans. China Development Bank and the Export-Import Bank of China have been central to financing both domestic HSR lines and international rail projects under the Belt and Road Initiative.
How HSR Has Restructured China’s Economic Geography
The most consequential impact of high-speed rail is what it does to economic distance. When a city is 90 minutes from a tier-one hub rather than four hours by conventional train, it enters a fundamentally different economic zone.
Zhengzhou illustrates the pattern clearly. Before HSR, it was a secondary logistics node in central China. After integration into the high-speed network — with connections to Beijing, Shanghai, and Xi’an — it became one of the most important inland manufacturing hubs in the country. Foxconn chose Zhengzhou for its largest iPhone assembly campus partly because HSR gave workers and engineers commutable access from surrounding cities. The Zhengzhou airport economy zone now handles more than 70 percent of iPhone exports by volume.
Wuhan tells a similar story, leveraging its HSR junction to attract automotive, semiconductor, and pharmaceutical investment. China’s port and logistics infrastructure increasingly functions as an integrated system with the HSR network, with inland cities acting as extended nodes for coastal ports like Ningbo-Zhoushan and Tianjin. Research by Chinese urban economists shows that cities within a two-hour HSR radius of a tier-one hub experience higher wage growth, greater inward investment, and faster service-sector development than comparable cities lacking HSR access.
CRRC, Technology, and the Rolling Stock Supply Chain
Rolling stock comes almost entirely from CRRC Corporation Limited, the state-owned manufacturer that emerged from the 2015 merger of CNR and CSR. CRRC produces the Fuxing (Rejuvenation) series of trains, which operate at 350 km/h on the Beijing-Shanghai and Beijing-Guangzhou corridors. The CR450, under development since 2021, targets sustained speeds of 400 km/h — a capability no other commercial train in the world currently matches.
China Railway Construction Corporation (CRCC) and China Railway Engineering Corporation (CREC) handle the civil infrastructure: bridges, tunnels, and the precision-graded trackbed that high-speed operations require. Together, these entities form a vertically integrated rail industrial complex that has driven construction costs down through scale and standardization. CRRC has leveraged this technology base to win rail contracts globally, from Boston to Buenos Aires, translating domestic scale into export competitiveness.
Foreign companies supplying components to the Chinese rail market — signaling systems, track maintenance equipment, or safety technology — typically need to operate through joint ventures or local subsidiaries, with technology transfer expectations that require careful IP structuring.
The Debt Load and What It Signals About Future Opportunities
China Railway’s total liabilities grew from approximately RMB 4.2 trillion in 2018 to over RMB 6 trillion by 2025. Annual interest expense exceeds RMB 200 billion. Profitability at the network level depends on high-density corridors cross-subsidizing lower-density lines built for political development goals in western and central China. The Beijing-Shanghai corridor is consistently profitable; many secondary lines are not.
The National Development and Reform Commission has moderated the pace of new HSR approvals since 2020, focusing on completing planned corridors rather than approving major new builds. This signals that the primary construction boom is maturing. The commercial opportunity is shifting from civil construction toward operations, maintenance, technology upgrades, and passenger experience services — areas where foreign firms with proven technology can compete more effectively than in civil construction. The U.S. Federal Railroad Administration regularly references China’s HSR network in its international benchmarking publications — a useful resource for American policy professionals and infrastructure investors comparing global models.
International Strategy: HSR as a Trade Infrastructure Variable
Indonesia opened its Jakarta-Bandung HSR line in 2023, built with Chinese financing and CRRC rolling stock. Thailand and Malaysia have advanced negotiations on similar projects. These transactions typically involve China Development Bank or Export-Import Bank loans, Chinese construction contractors, and CRRC trains — a vertically integrated export package that competes directly with European and Japanese alternatives. For Western infrastructure firms, competing with this bundled model requires creative financing structures, differentiated technology positioning, and long-term relationship investment in host-country governments.
For supply chain strategists, the connectivity HSR provides between coastal manufacturing zones and inland labor markets directly affects where multinational companies site operations. A business evaluating locations in Chengdu, Xi’an, or Zhengzhou today is evaluating not just local labor costs but HSR-enabled access to engineering talent, executive management, and cross-China logistics. The State Council of China publishes regular updates on rail network expansion and regional development policy — the authoritative primary source for investors tracking the network’s evolution.
Practical Implications for Foreign Businesses
Site selection reviews should explicitly model HSR travel times from candidate locations to tier-one hubs, major ports, and other company facilities in China. A location that was peripheral ten years ago may be fully integrated into the network today. A site relying on conventional rail or highway may be disadvantaged relative to equally priced HSR-connected alternatives.
Talent strategy is affected as well. Senior Chinese engineers and managers who once required Shanghai or Beijing postings to maintain career development connections are increasingly willing to accept tier-two city positions when HSR allows them to reach tier-one hubs in under two hours. This expands the talent pool for inland operations and changes the executive recruitment calculus.
For companies in infrastructure, construction materials, technology, and passenger services, the shift from HSR construction to HSR operations creates distinct opportunities. Maintenance contracts, station retail and hospitality, and data analytics for ridership optimization are areas where the government’s focus on service quality — rather than network expansion — is creating new entry points for foreign participation.
China’s high-speed rail network is no longer a marvel of engineering ambition. It is operational infrastructure embedded in the daily economic calculations of 1.4 billion people and thousands of businesses. Treating it as background context rather than an active variable in China strategy is an increasingly costly analytical error. The U.S. Department of Commerce’s transportation industry resources offer useful comparative data on rail infrastructure investment trends relevant to businesses evaluating US-China logistics strategies.